The Canadian Sphagnum Peat Moss Association (CSPMA) released a report on Sept. 17 covering harvest conditions through Aug. 31, and the regional results vary widely. Alberta reached 56% of expected extraction, Manitoba 79%, Saskatchewan 90%, Québec's North and South Shores 77%, Southern New Brunswick 70%, Northern New Brunswick 85%, and Ontario 90%. Prince Edward Island, Newfoundland and Labrador, and Nova Scotia were reported as significantly below expected levels.
The association attributes much of the shortfall to wet weather, and it says careful inventory management should allow producers to meet customer needs. That distinction matters. This is not a call to declare a peat shortage.
The Number Behind the Number
It is, however, another reminder that an agricultural raw material harvested outdoors will never be fully insulated from weather. CSPMA's "expected extraction" is also not a measure of how much available peatland was harvested. It is the amount producers calculated they needed for the season: market requirements plus the desired year-end inventory buffer, minus inventory carried into 2026. That definition shapes how the percentages should be read.
The more useful question for growers, then, is not whether peat will run out. It is how resilient a growing-media strategy is when one of the materials it depends on becomes harder or more expensive to secure.
The Risk Is Bigger Than Peat
Peat is only one part of a broader supply picture. Climate affects harvest and biomass availability. Labor affects harvesting, processing and transportation. Freight can change the economics of a material long before its FOB price changes.
Transportation is especially difficult right now. The Wall Street Journal reported in late September that U.S. contract trucking rates averaged $3.11 per mile in August, including fuel surcharges, up 29% from a year earlier. Diesel, driver availability, rail surcharges and ocean freight are all adding volatility. For a bulky input such as growing media, delivered cost can change the answer to a sourcing decision very quickly.
Dr. Charlie Hall has made a similar point from the broader grower-cost perspective. In a recent Greenhouse Grower interview, he emphasized supply-chain agility, backup suppliers and working-capital discipline as growers plan for 2027. His Index of Prices Paid by Growers is useful precisely because the cheapest input on paper is not necessarily the lowest-risk or lowest-cost decision once freight, inventory and operational impacts are included.
That is why growers should stop treating raw-material selection as a once-a-year purchasing exercise. It is becoming a risk-management and production-design decision.
Start With Crop Character, Then Back Into Ingredients
Growing media is often built in the opposite direction from the way it should be. The usual starting point is what is available — peat, coir, bark, wood fiber, perlite or another familiar component — and the mix is built around those ingredients.
A better starting point is the crop. What character does the root zone need? How much water holding? How much air porosity? What structural stability is required through the crop cycle? How does the material need to rewet? What buffering and chemistry can the crop and irrigation program tolerate? How uniform does it need to be for automation?
Once those requirements are clear, the ingredients and percentages that can create that character follow.
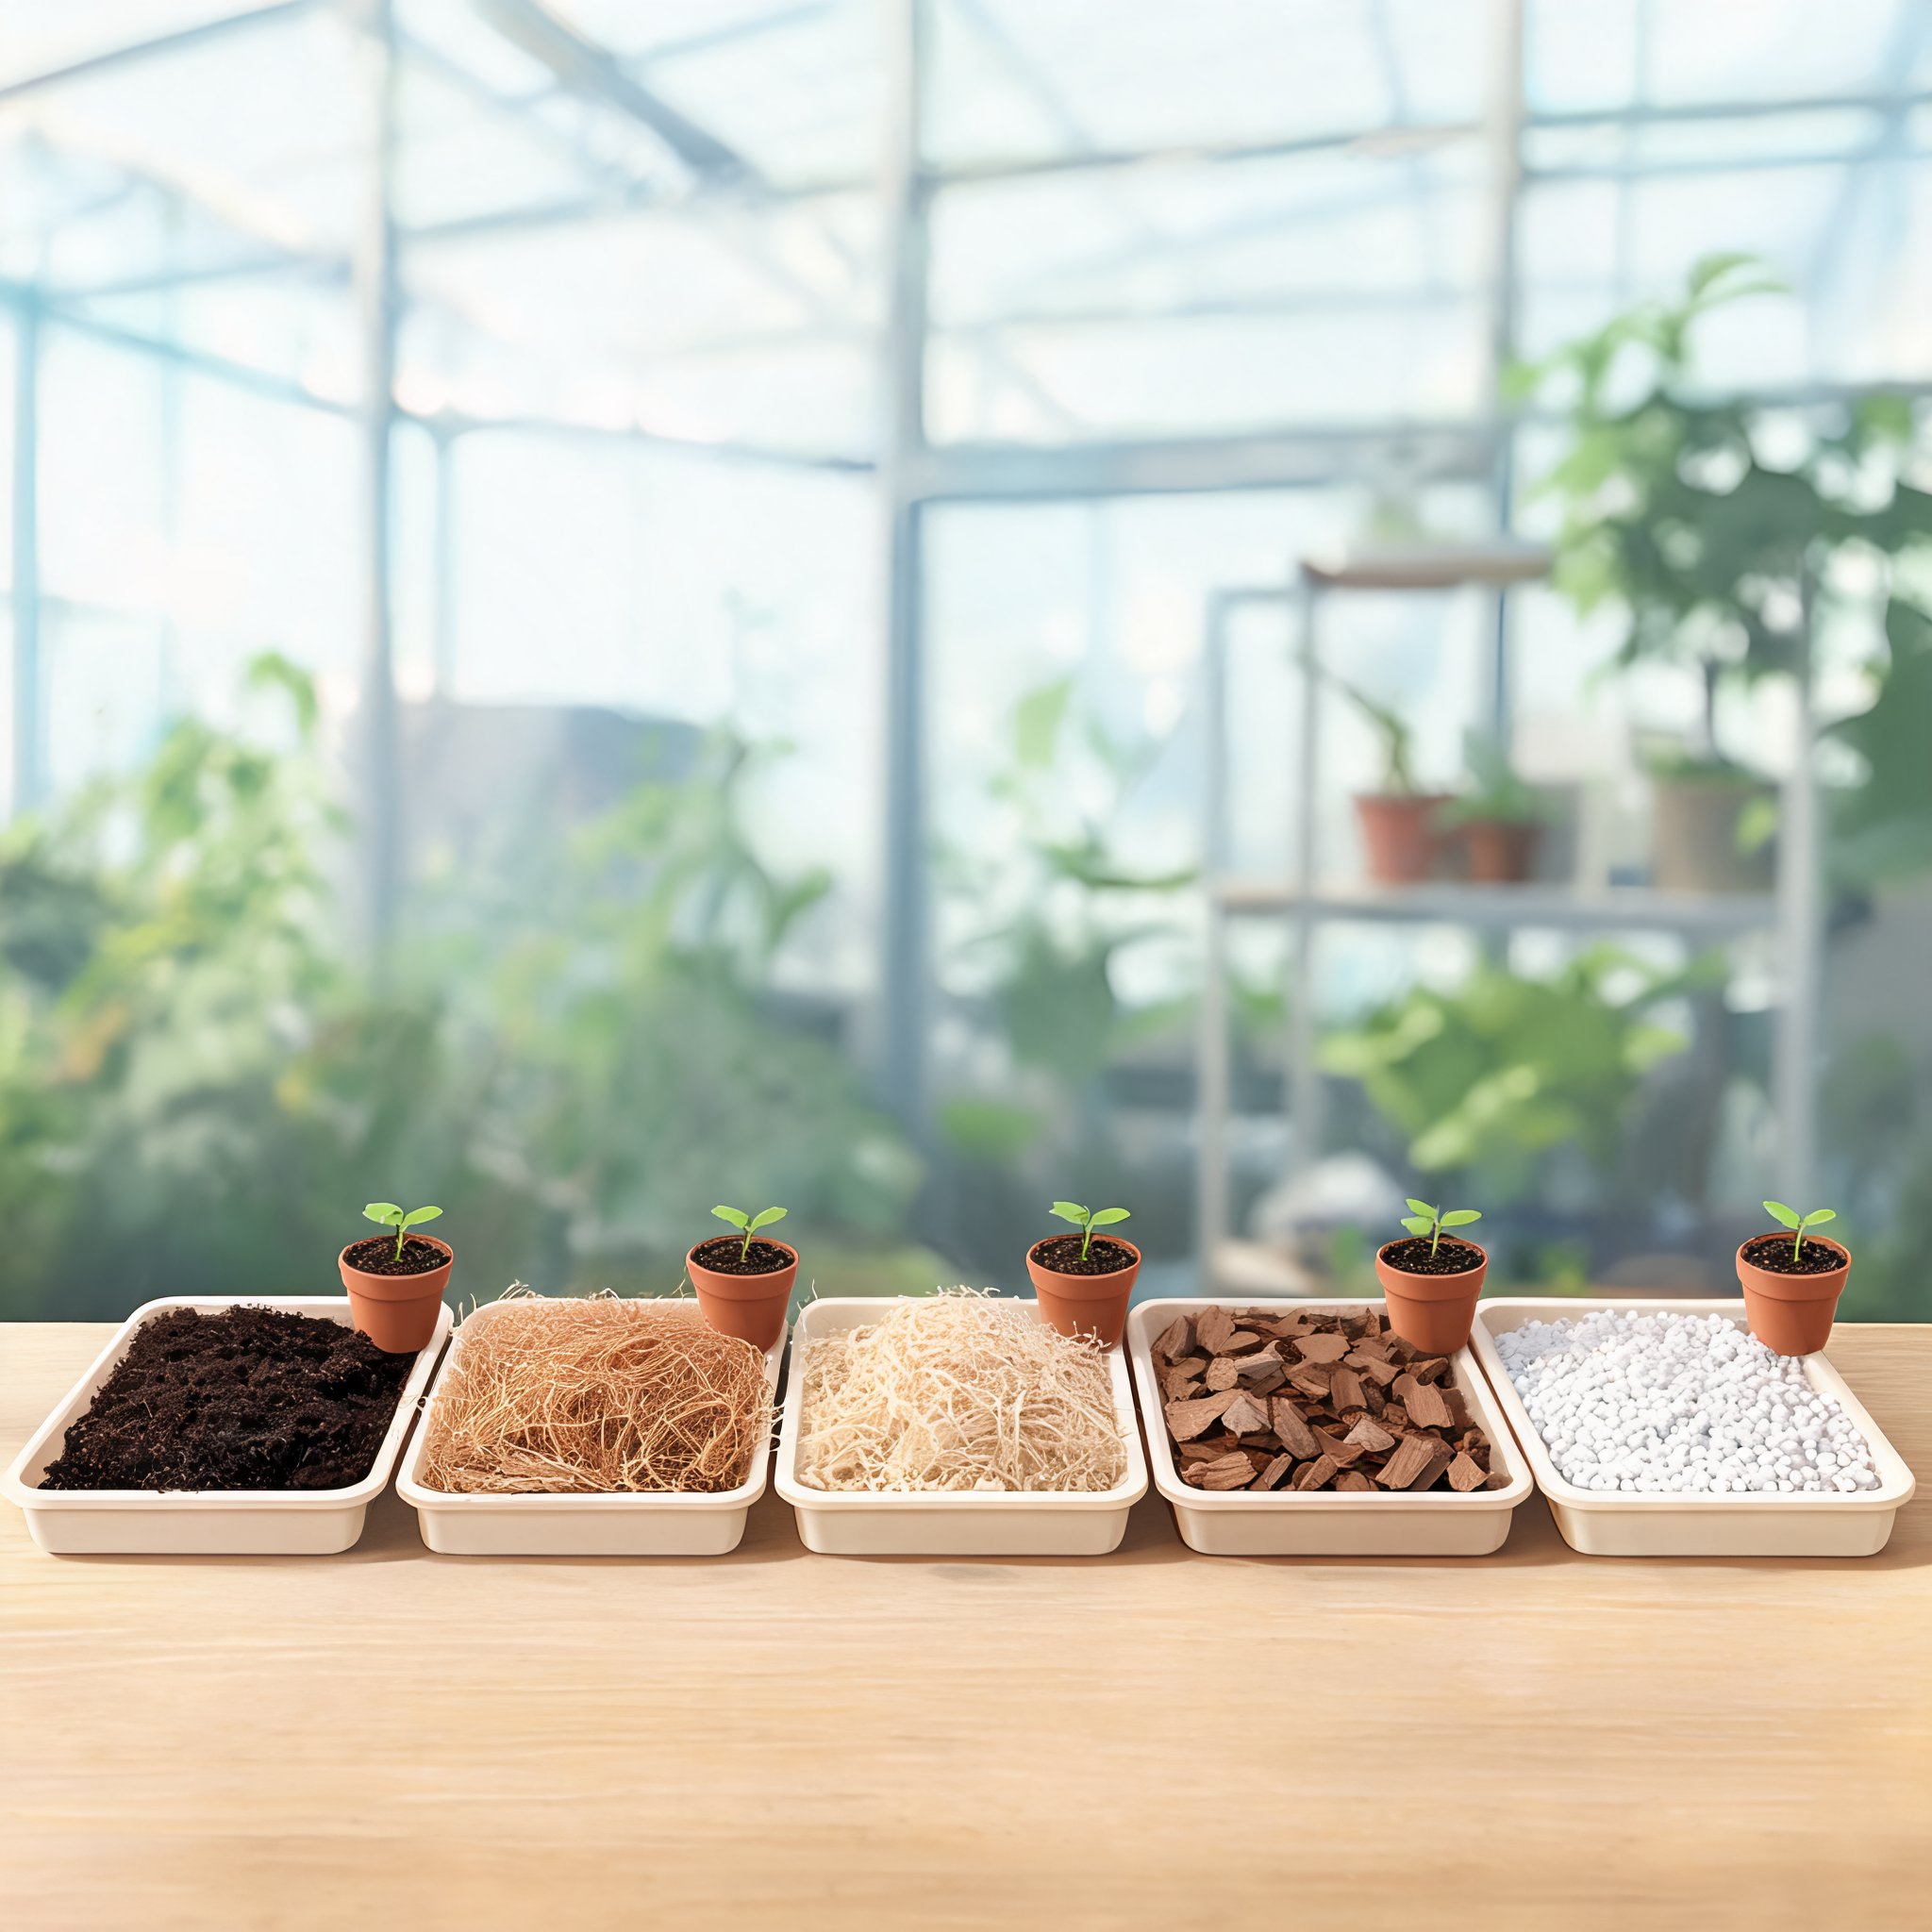
This matters because the raw-material toolbox is getting larger. Wageningen University & Research's 2026 work on the future of growing media identifies familiar, market-accepted materials such as coir, coniferous wood fiber, bark, compost and perlite, but also less familiar candidates including other plant fibers, biochars, co-composts and reused growing media. The researchers make an important point: many new materials require processing, sanitization and stabilization before they can become reliable horticultural inputs. Availability is not the same as suitability — but suitability is increasingly something that can be engineered.
Revisit the Materials You Passed Over
Processing technology has continued to improve across coir, wood fiber, bark and other biomass streams. Materials that were too inconsistent, too wet, too coarse, too salty, too difficult to handle or simply too expensive several years ago may deserve another look. The same is true of regional agricultural residues that can be cleaned, screened, fiberized, composted or otherwise stabilized into more consistent horticultural ingredients.
That is not an argument for replacing a proven substrate simply because something new is available. It is an argument for knowing what else is out there before it is needed. A material also does not have to become 30% or 40% of a formulation to be useful; in some systems a 5% or 10% inclusion may be enough to change cost, water behavior, structure, rewetting or supply exposure. The right inclusion rate is a crop and system question, and any new component needs to be trialed and validated before commercial adoption.
Local and Global Are Not an Either/Or
Interest in sourcing closer to home is understandable. Regional materials can reduce transportation exposure and create flexibility, particularly when they can be processed near the point of use. But "local" is not automatically better, just as "imported" is not automatically risky.
Coir, for example, travels a long distance but can offer characteristics that are difficult to reproduce with some local materials. Peat remains an extraordinarily important and effective growing-media component. Wood fiber and bark can make excellent contributions where feedstock and processing are right. Other biomass streams may become more useful as processing improves.
A more resilient strategy is likely to be a portfolio: dependable core materials, strong supplier relationships, some regional options, some globally sourced options, and enough formulation knowledge to adjust without losing the root-zone character the crop requires.
Use This Season as a Planning Signal
The lesson from this year's Canadian peat harvest is not that growers should move away from peat. CSPMA itself says inventory management should allow producers to meet customer requirements. The lesson is that the conditions behind raw materials can change quickly, while crops still have to be produced on schedule.
Growing-media demand is also expanding. Wageningen research projects global demand rising substantially toward 2050, which means the industry will need a broader basket of materials and more processing capacity — not simply a different winner in the peat-versus-coir-versus-wood-fiber debate.
For growers planning 2027, the practical questions are worth asking now: Which raw materials are most exposed in the current formulation? What is their true delivered cost? Which characteristics are essential to the crop? What other ingredients could deliver part of that function? And which of those should be trialed first?
Do not wait for a shortage to learn how another raw material behaves. The best time to build flexibility into a growing-media program is while there are still choices.